That highlights yet another layer of the scam. Before any shopper visits the site, the fraudster must build trust with the user's bank in order to accept online payments as a seemingly legitimate merchant. To pass identity verifications and risk assessments required by the merchant banks, called acquirers, many scammers come armed with top-notch cybersecurity and legitimate business registration documents. But they also have to stand up to ongoing scrutiny, as banks can pull the plug on these merchant accounts at any time if suspicious activity comes to light.
When a merchant’s behavior starts to raise concerns, the Franchise GRIP team investigates, gathers evidence and shares it with the acquirers, which then decide what action to take, including severing their relationship with the merchant. After the GRIP team did a deep dive into Get Wuffy’s enablers, Soares and his colleagues presented the evidence of the scam merchant to the acquirer, which terminated the relationship and added the scam merchant to MATCH Pro, Mastercard’s database of merchants terminated for specific causes, including fraudulent activity.
“Every fraud environment is an adversarial one, and with each rule introduced by payment networks, adversaries learn to adapt to skate just outside the line,” says Cathal Smyth, Mastercard’s director of cyber analytics. “But eventually, the signals start to add up. If we look hard enough, we can find the threads that tie it all together.”
In the wake of this success, Kanwal and his colleagues are accelerating the company’s coordinated global approach to disrupting scams. Their goal is to capitalize on the working group’s holistic view to disrupt every stage of the criminal enterprise: improving the detection of scam payments; helping acquirers identify and reject more fraudsters before money changes hands; and encouraging victims to report deceitful merchants after the fact.
The same principle extends across the broader fight against scams. When intelligence is shared across the ecosystem, financial institutions can gain more context to identify suspicious activity earlier, whether that risk emerges through a merchant, a payment or the account receiving the funds.
"For too long, the onus on scam prevention has been placed largely on consumers,” says Ann Johnson, who leads Mastercard’s Security Solutions business. “The bigger opportunity is for the ecosystem to work together to protect consumers from scams, through better intelligence, stronger safeguards or earlier intervention.”
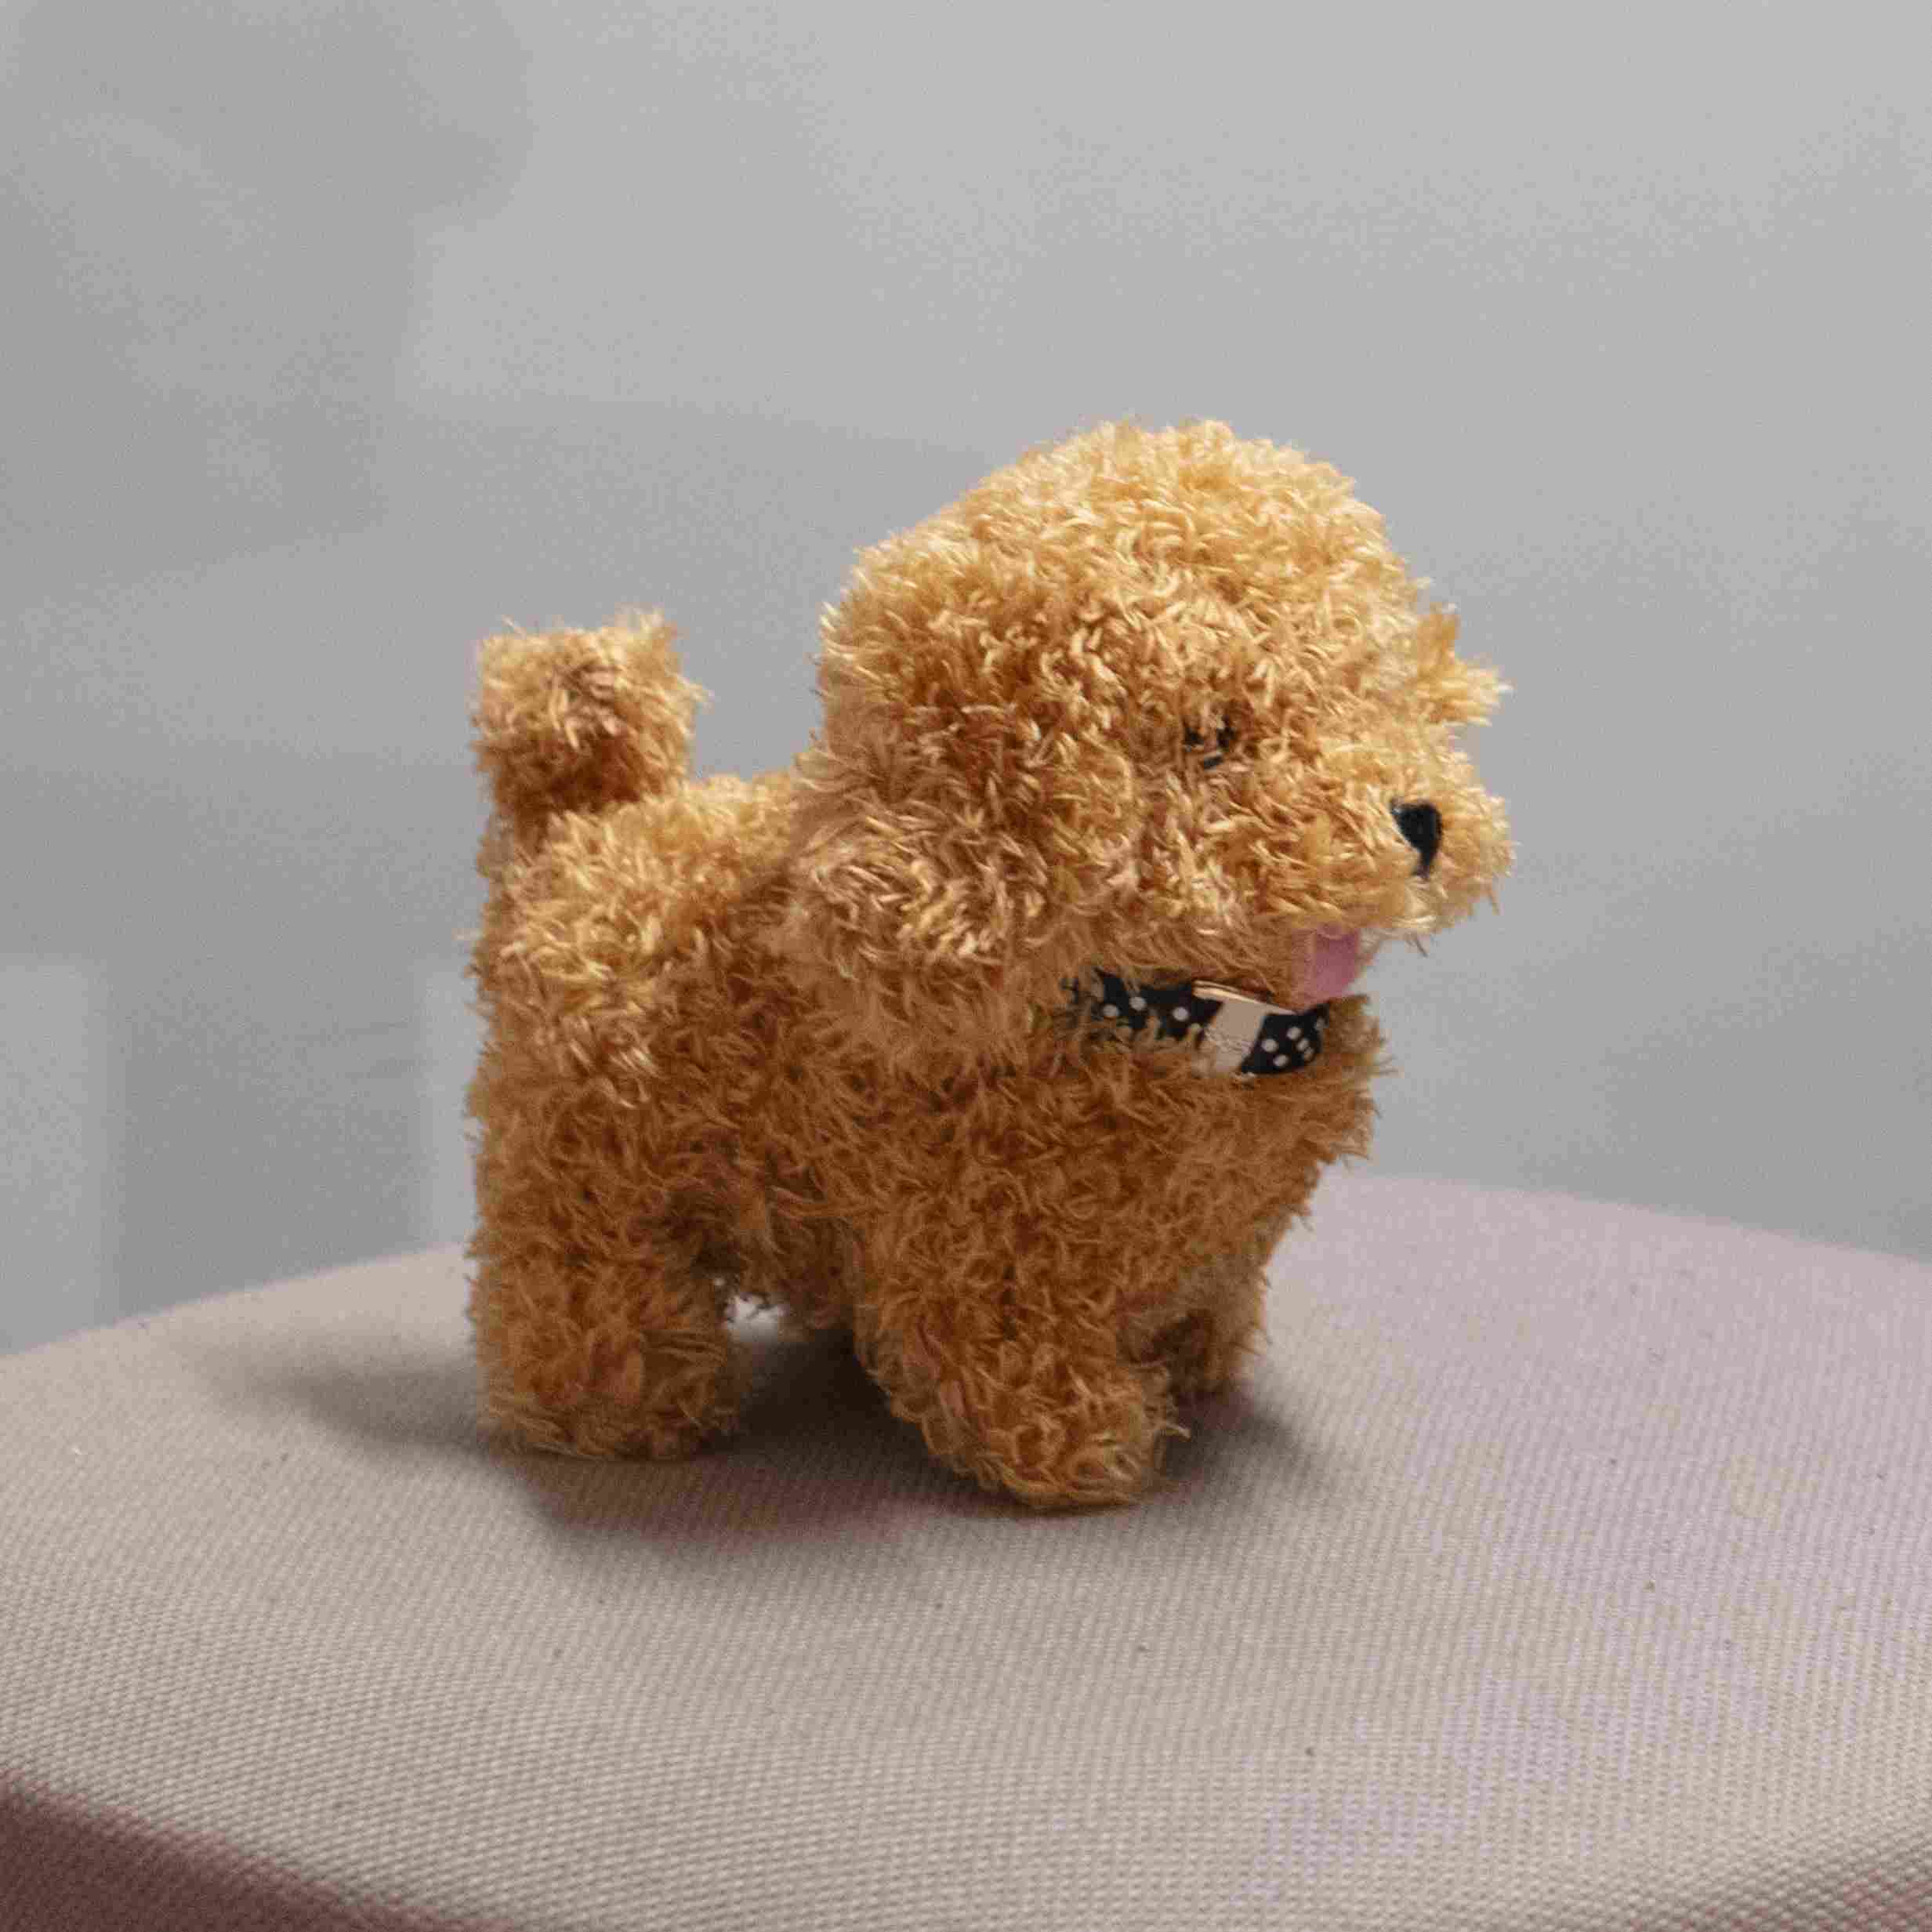
And what became of Wuffy, the little robotic dog who started it all?
“It’s still at my house,” Kanwal says. “My wife is not happy about it.”