Buying a home — particularly your first — can feel exciting, confusing, and overwhelming all at once. It can be difficult to assess how much a home is truly worth (and what your offer should be) when the process is new to you.
To tackle this important decision, consider these factors to help determine if you’re making a good investment at a fair price.
If you’re not sure how to set a budget for your first home, use this formula: Your total household income (before any deductions, such as taxes) x 0.28. This number is the maximum you should aim to spend on your mortgage, so it stays at or below 28% of your total income.
Why 28 percent? Experts recommend this number to ensure you can comfortably afford your housing while saving money for other essential expenses including food, transportation, and debt. While it’s not a hard and fast rule, it’s a good place to start.
According to the National Association of REALTORS®, the typical down payment for first-time buyers is 8% of the home’s cost. Be prepared to pay a chunk of your home’s price upfront. The good news is you can subtract that portion from the amount you need to borrow for the mortgage.
If you choose to buy a home directly from the owner (For Sale By Owner) — meaning no selling agent is involved — it could be a big risk. This is because most homeowners don’t have professional experience in real estate and may overestimate their home’s value. They also may not be completely honest about any problems with the home.
If you choose to take that risk, make sure the asking price is at least 10% below what it would be through a real estate agent.
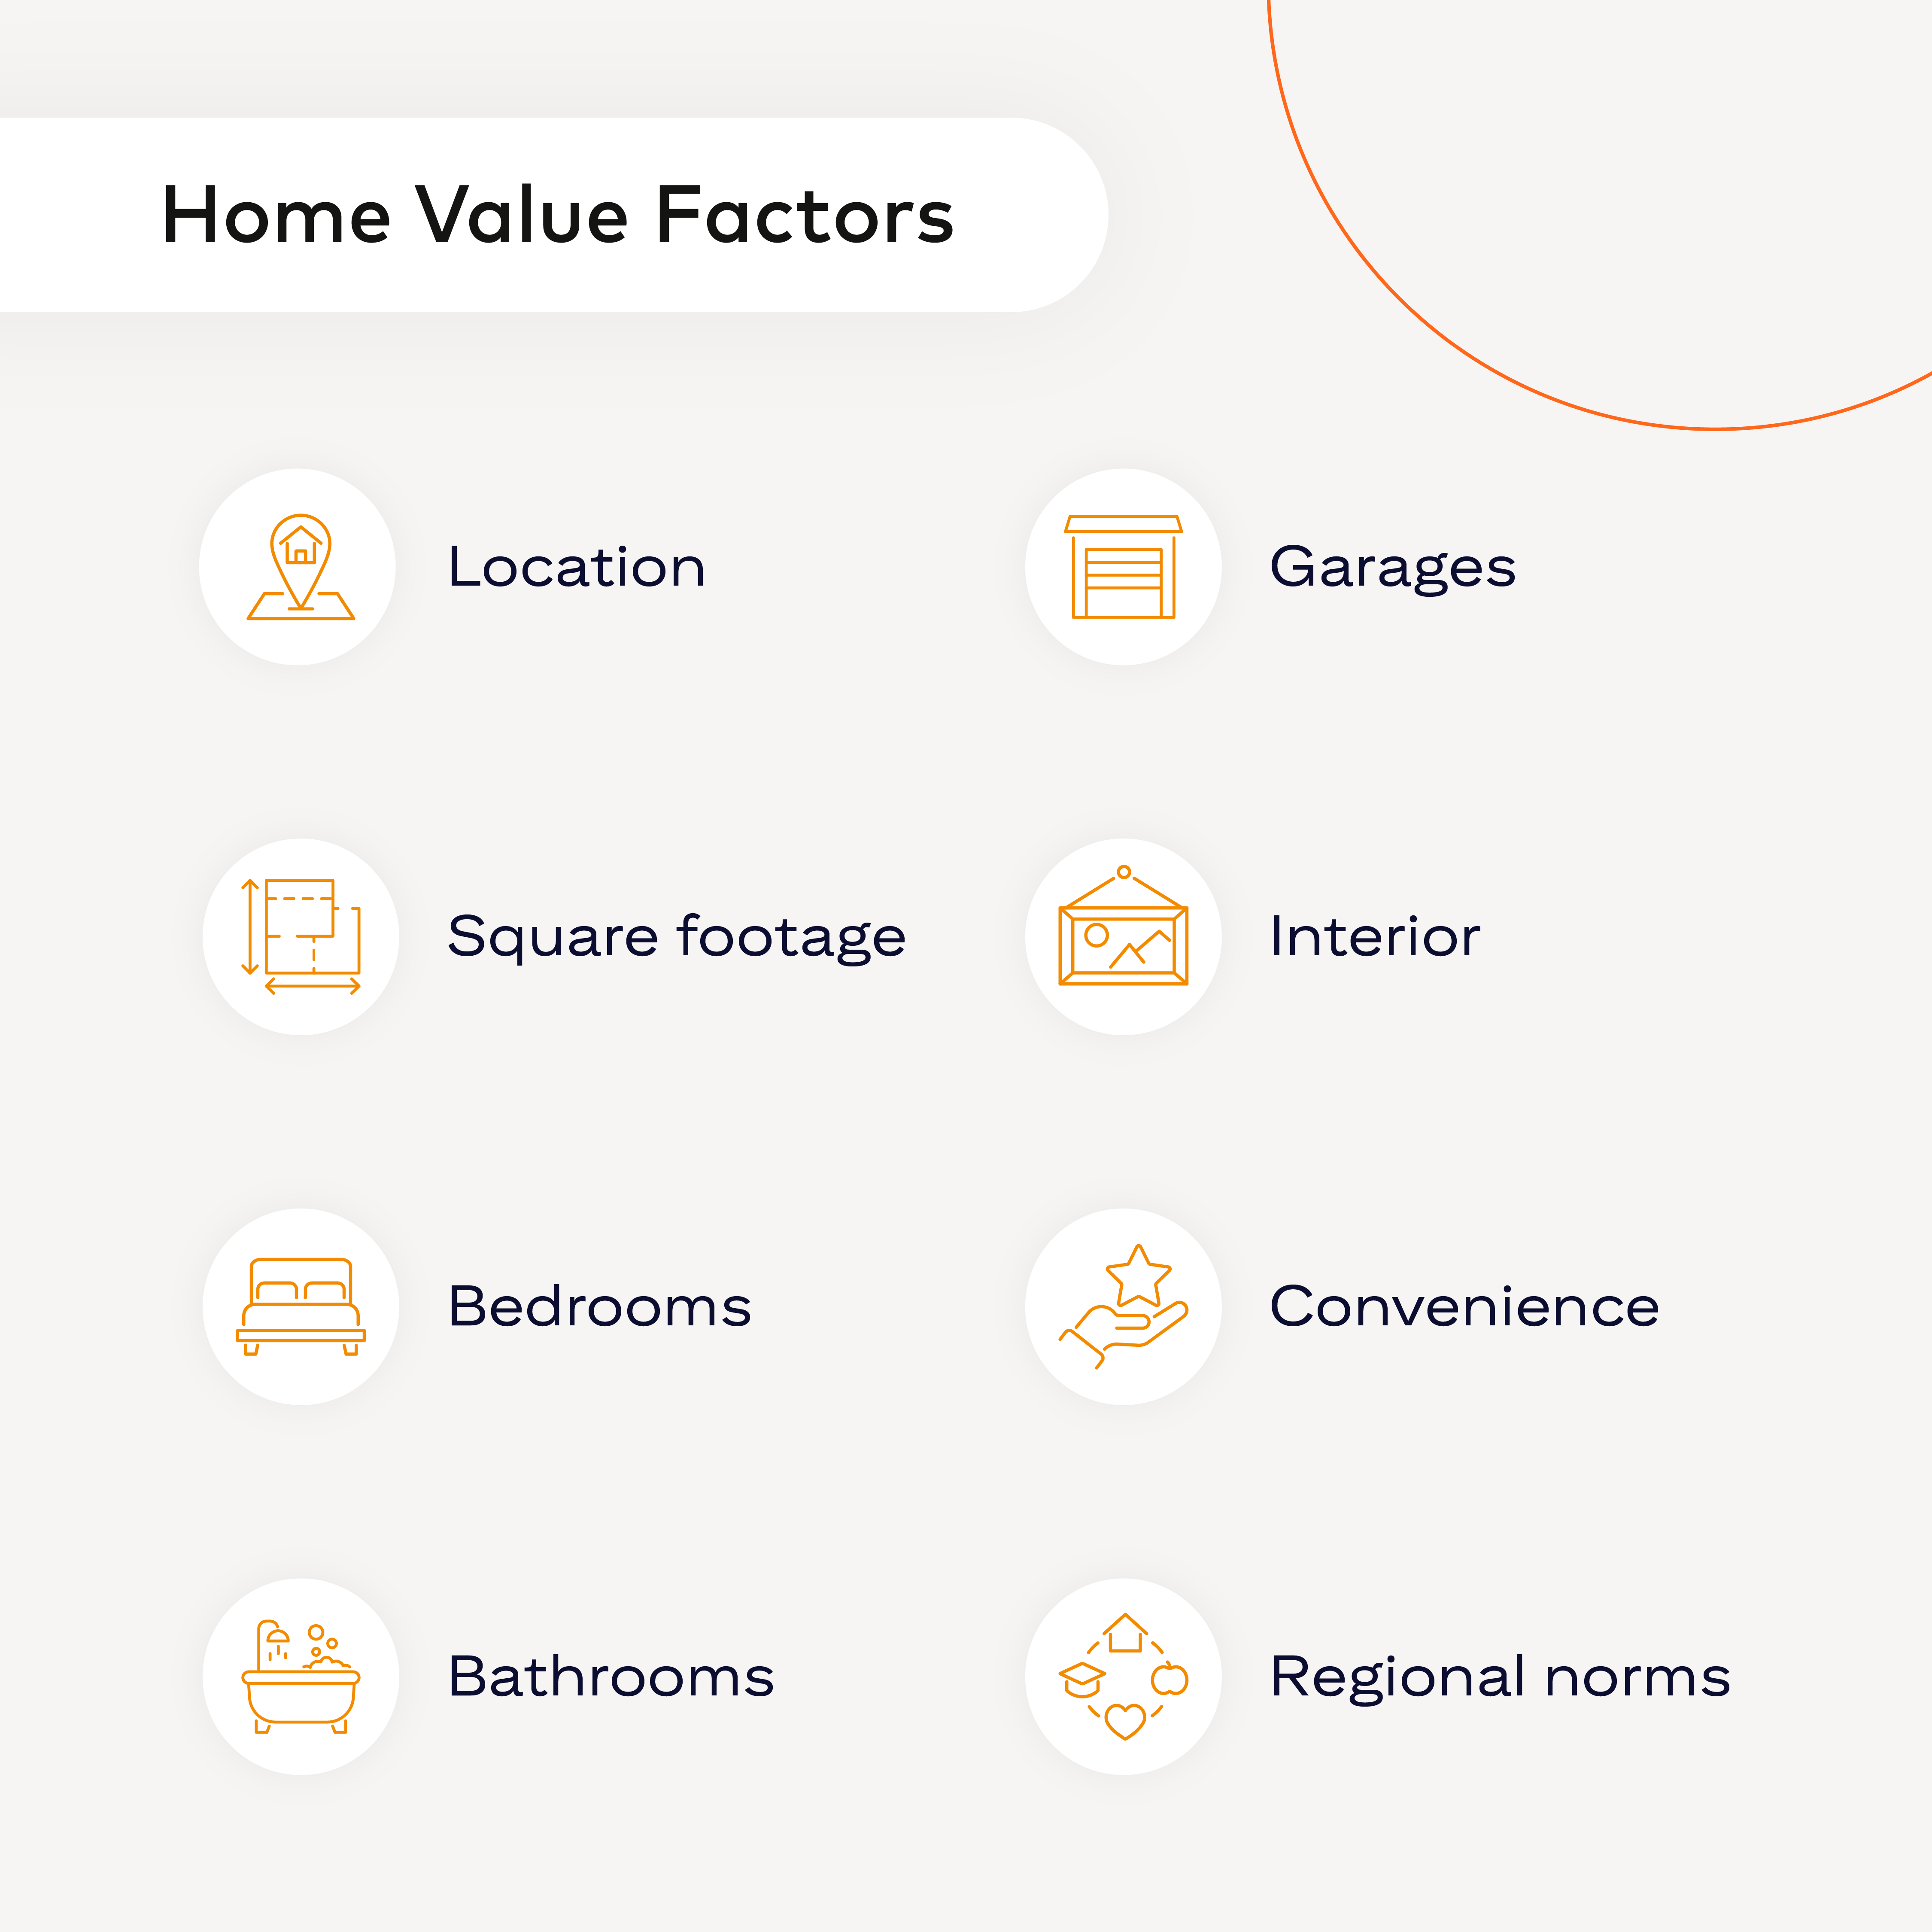
When it comes time to assess if a home is a good investment, here are some factors to consider.
1. Location: Does the home back up to commercial businesses or the interior of a neighborhood? The market's reaction to location will vary from place to place, and these features can be desirable in one area while undesirable in another.
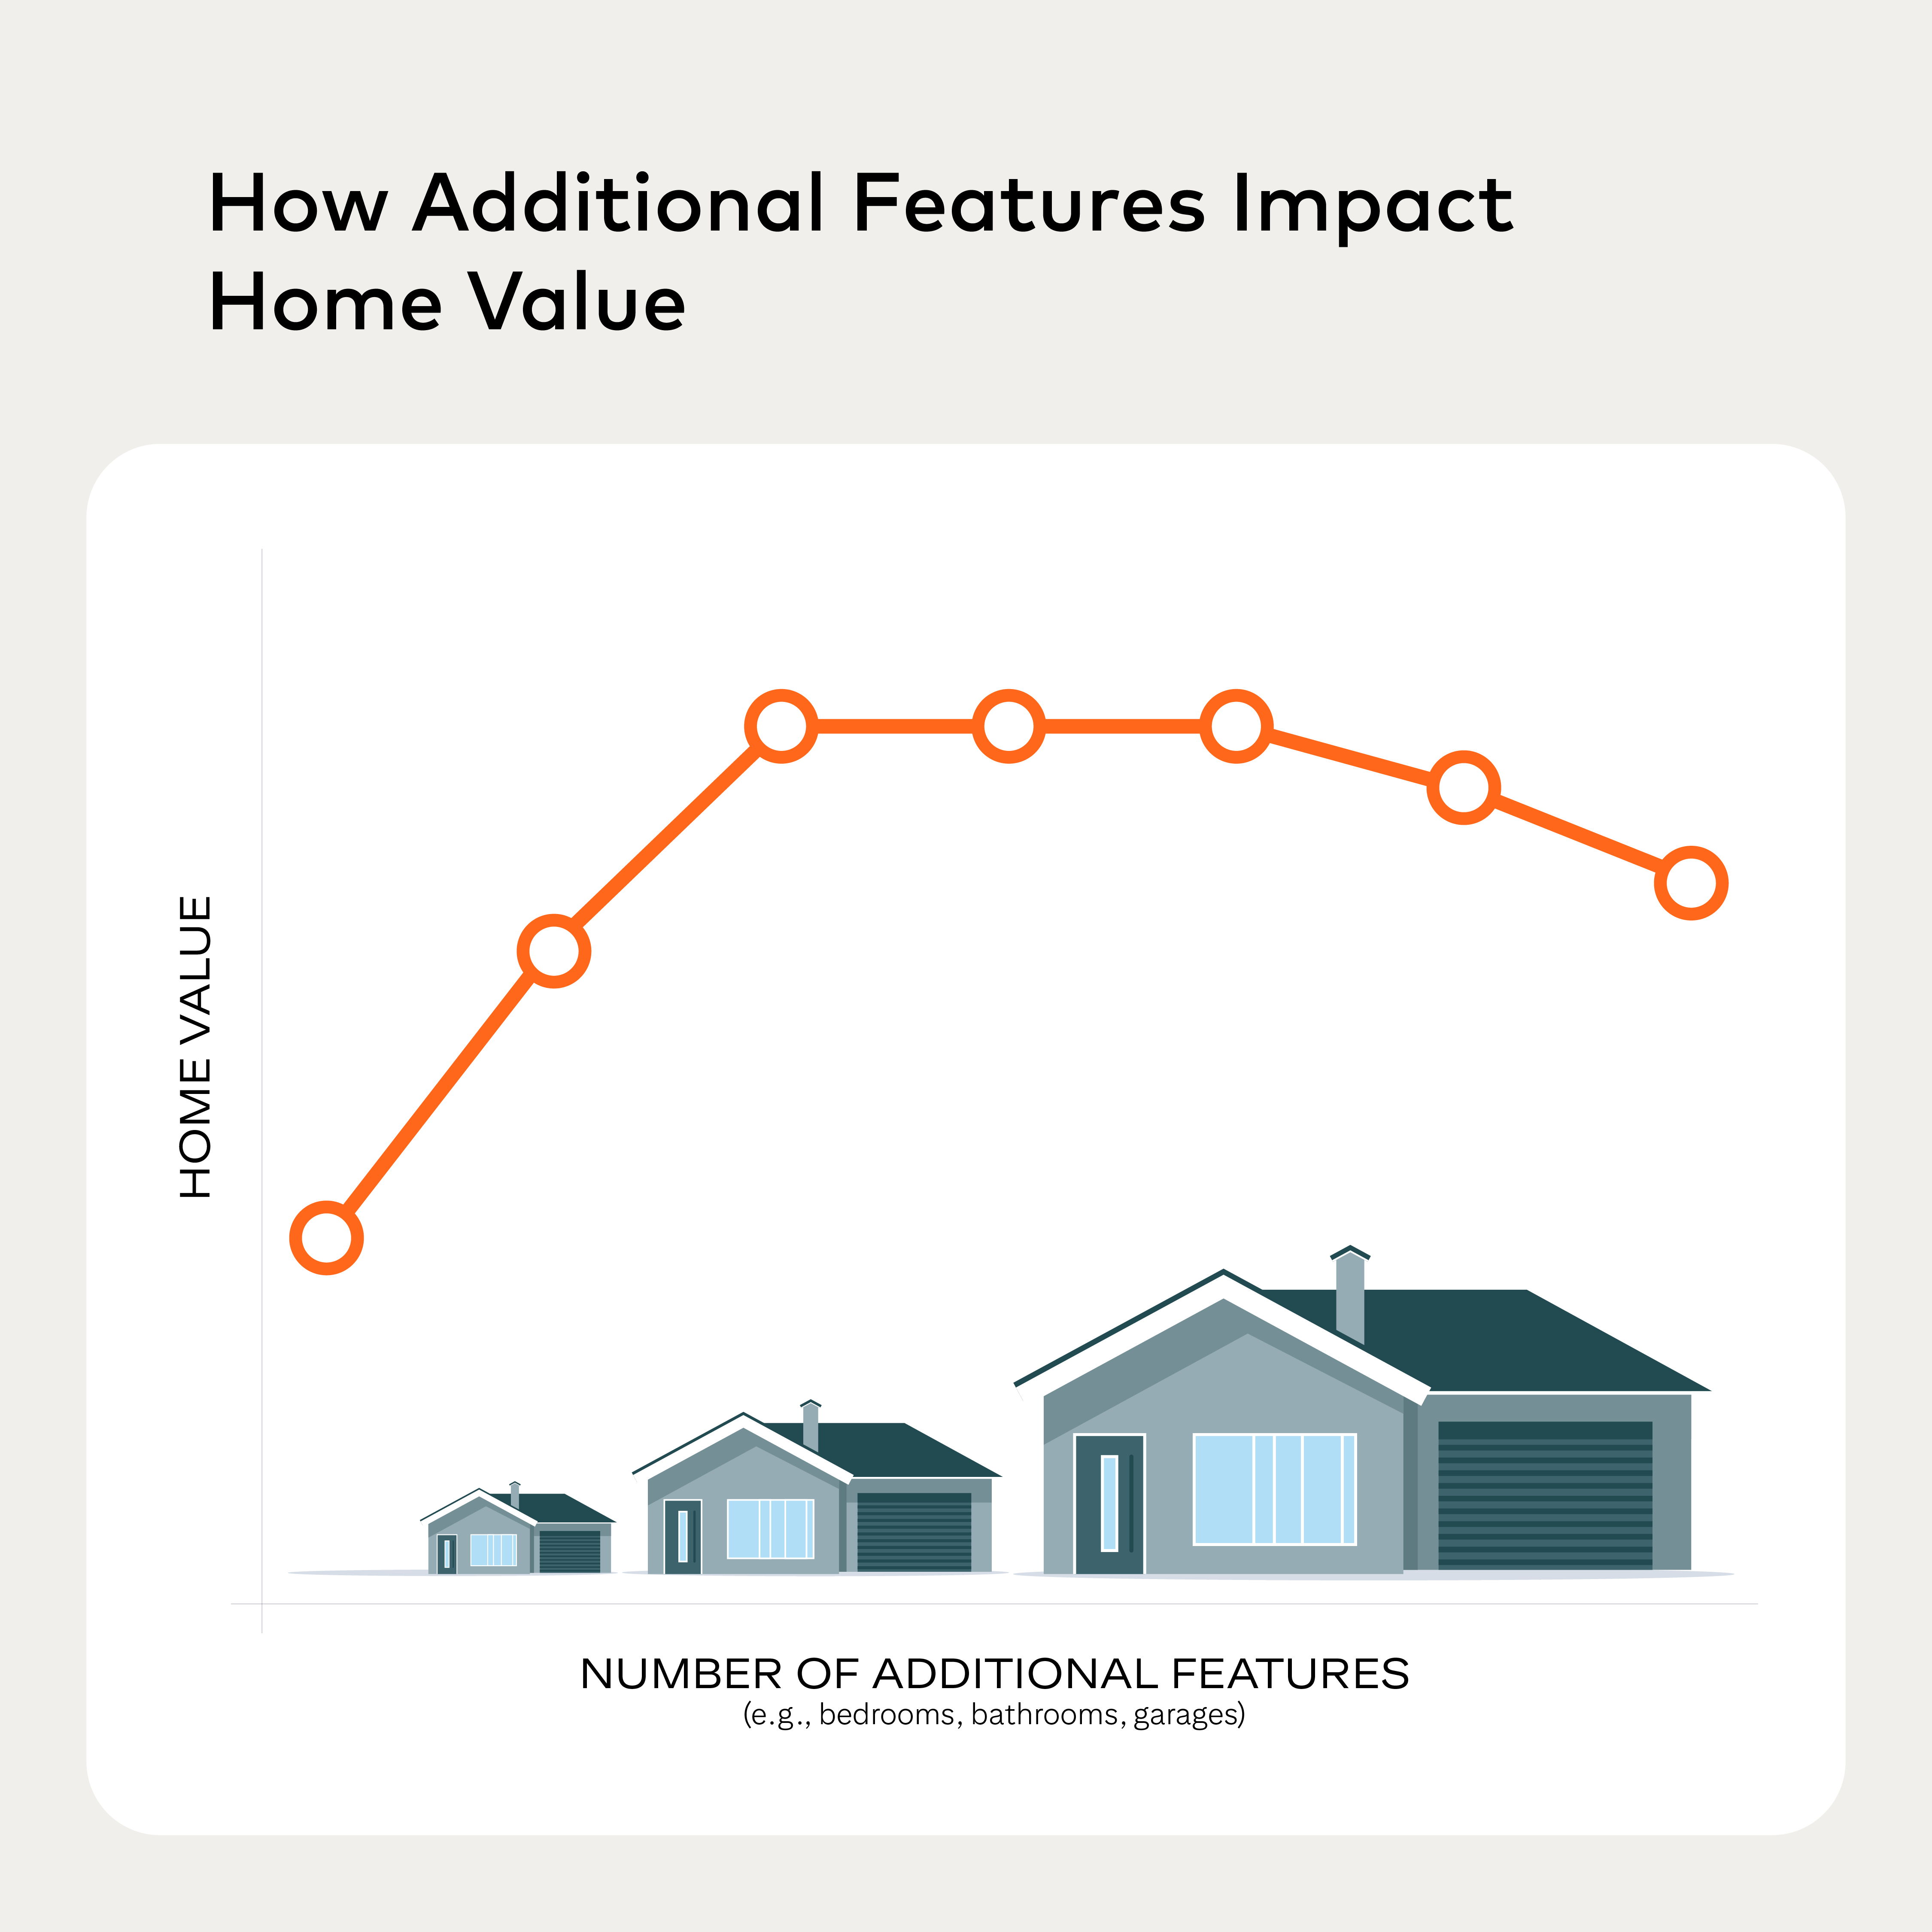
2. Square footage: Anything greater than the standard size of 1,500-1,800 square feet will add value, up to a point. As home size increases, however, the value per square foot decreases.
3. Bedrooms: A fourth bedroom adds substantial value while the value of adding a fifth, sixth or seventh decreases incrementally.
4. Bathrooms: The same goes for bathrooms: After two or two-and-a-half, the value of each added bathroom decreases. The third bathroom usually won't add as much value as the second bathroom.
5. Garages: There is a home-price jump from a one-car garage to two. However, there is not much value for anything above a three-car garage.
6. Interior: Custom cabinets, higher-quality countertops and high-end appliances will all add to the value of a home. So will a room's accessibility and functionality. For example, how easy is it to navigate the kitchen? What is the access like from the refrigerator to stove to sink?
7. Convenience: Proximity to public transportation is important in urban areas; accessibility to conveniences like highways and shopping are a plus in the suburbs. Features that inconvenience a homeowner will reduce value. Think of a kitchen on the second floor (common in modern two- or three-level condominiums) or entry through a garage or long hallway.
8. Regional norms: In some regions, it's the norm to have finished basements, attics or garages. These spaces aren't included in the livable square footage but can affect marketability and add some value.
As a first-time homebuyer, it’s unlikely you’re going to find a place that checks every single one of your boxes. Consider what matters to you most — whether it’s price, location, or the condition of the home. Understanding your must-haves and being flexible on the rest will help you navigate the process with more confidence and find a home that truly fits your needs.