There are many reasons people have difficulties saving — living paycheck to paycheck, wanting to live in the “here and now,” or just not knowing where to start. According to a recent Bankrate report, over a quarter of people don’t have any emergency savings at all.
If you haven’t started yet — that’s okay, you’re not alone. Here’s how you can get started.
A good first step is determining what you want to save for, such as tuition, a new car, or a wedding. Maybe you want to save for your future, hoping to retire early and comfortably. Whatever it may be, write it down, and be as specific as you can.
If you’re not sure what you’re hoping to save for, start with an emergency savings account. According to most financial advisors, you should have a safety net fund that covers three to six months of expenses in the event of a job loss or an emergency. That may sound challenging, but you can start with a small amount and build it gradually over time.
One way to do this is to have a portion of your paycheck (say, 5%) automatically deposited directly into your savings account, so that money isn’t available to you in your day-to-day spending. You can even give your savings account a name like “My Dream Home” to motivate you to continue putting funds there.
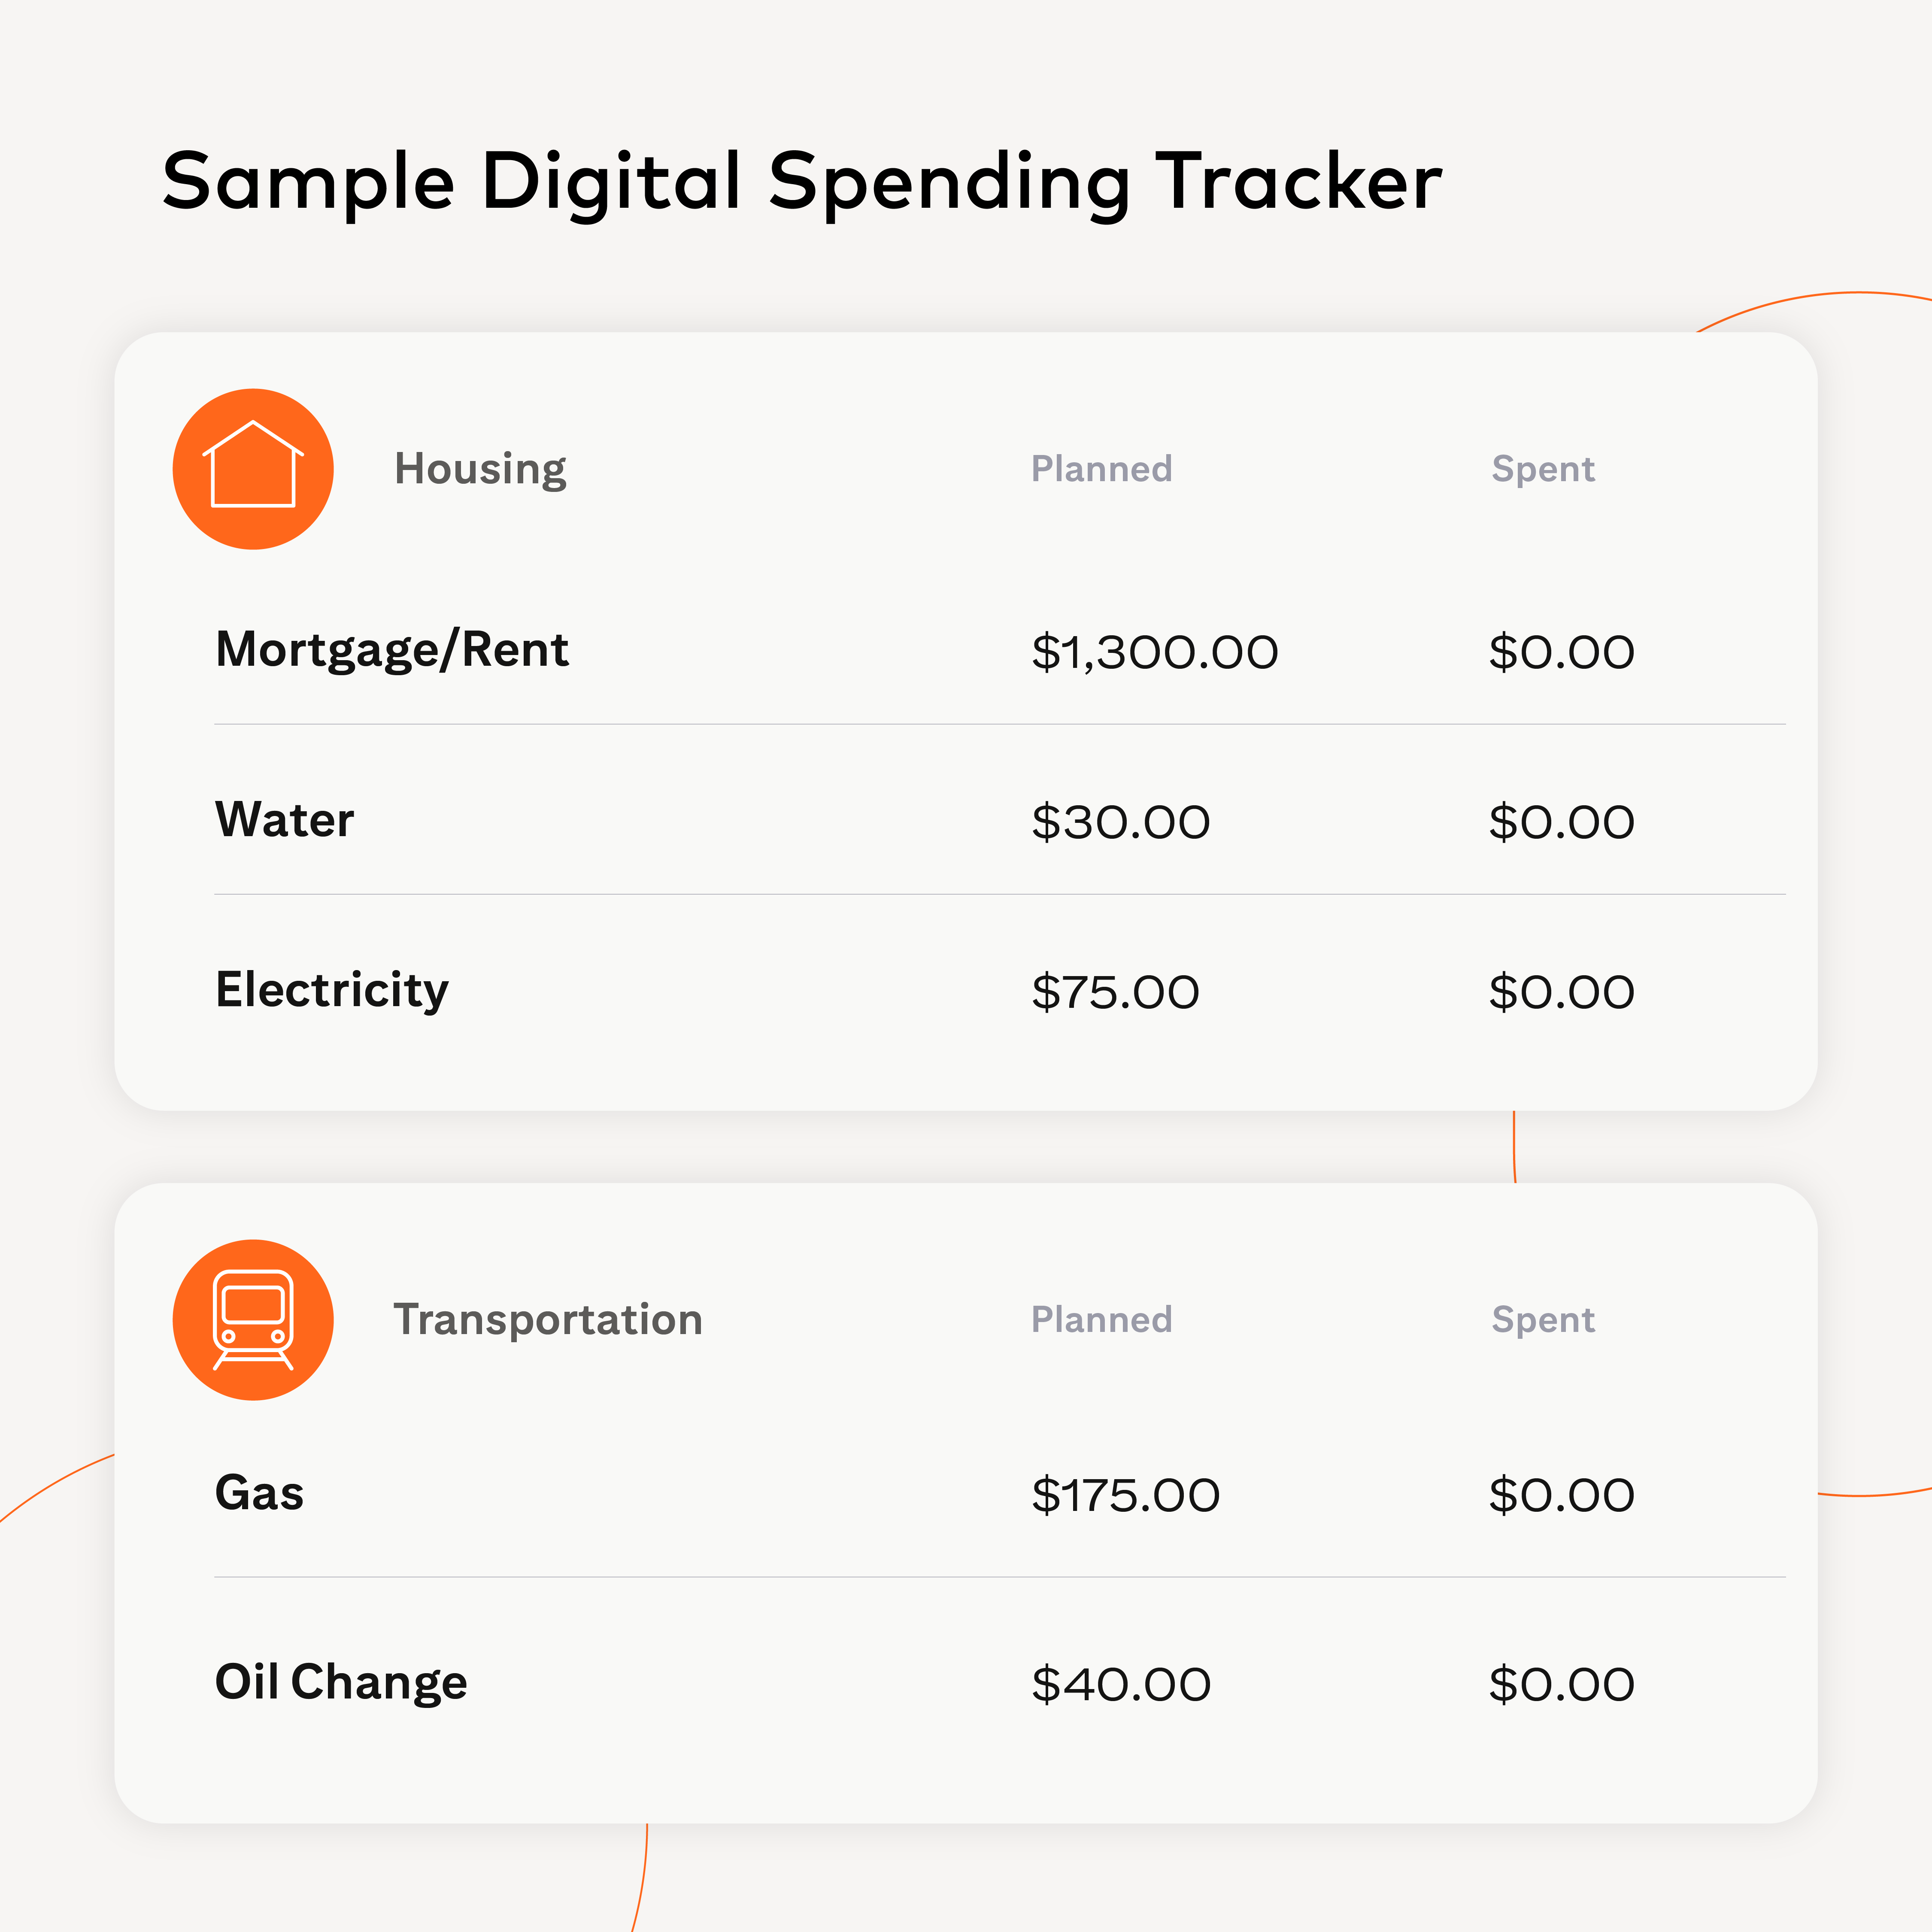
To make sure you're consistently spending in line with your income, it's a good idea to draft a budget. Start by recording every dollar you spend to understand exactly where your money goes each month. There are two ways you can do this:
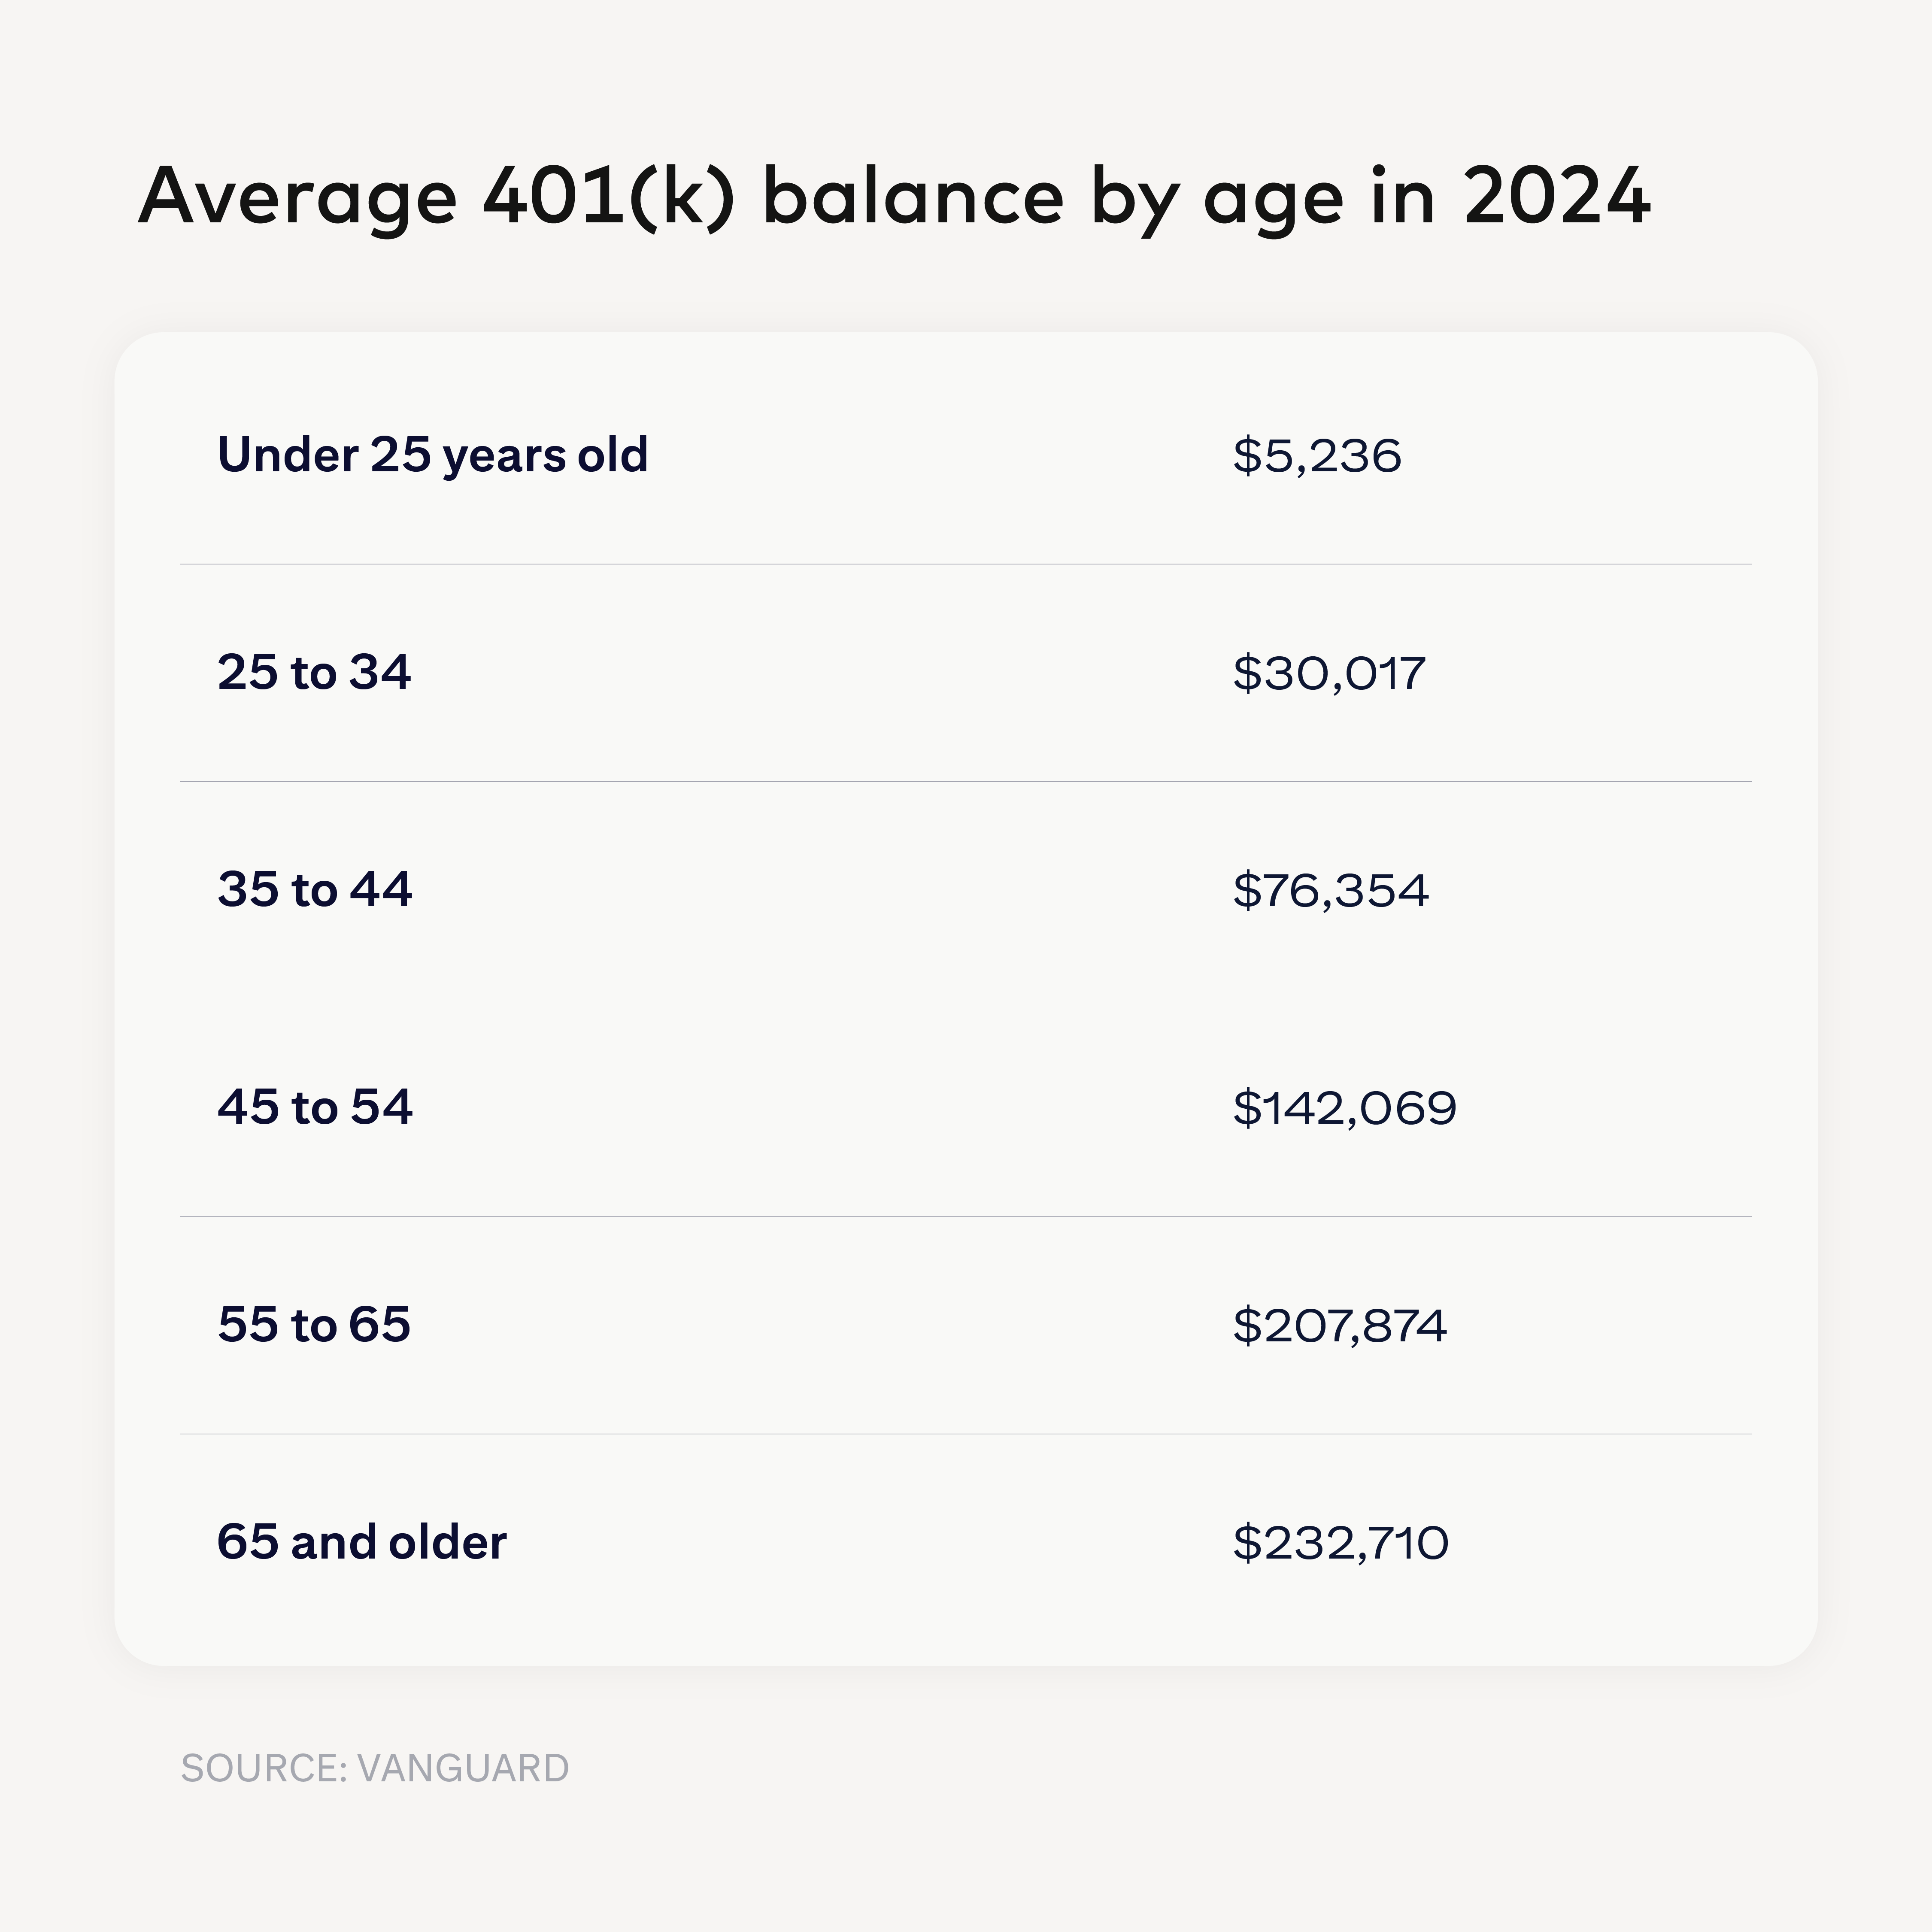
The sooner you start saving for retirement, the more it will compound over time and pay dividends by the time you retire. You may want to consider setting up an individual retirement account (IRA) or contributing to your company's retirement plan (e.g., 401(k) plan), if they offer one. Contributions to a 401(k) reduces your taxable income and, on top of that, companies often match 3% to 6% of the money you put in, in effect doubling your savings.
When used wisely, credit cards can help you save. Many credit cards offer cashback programs where you earn a percentage of your purchases back, or rewards points that can later be redeemed to save you money on flights, hotels, and even groceries.
You'll want to first evaluate the terms and conditions of the credit card reward program as well as the costs associated with that card before choosing to apply (or when you're reassessing your current cards).
Consulting a professional for a financial checkup is worthwhile. Financial advisors can help you establish long- and short-term savings goals, develop plans to pay down debt and offer advice to help you improve your credit score. The most important thing is to start saving as soon as you can, wherever you’re at, just a little bit at a time. Your future self will thank you.