Banking Basics: Types of Banking Institutions and Accounts

Two colleagues sitting in a café, discussing and pointing at a laptop screen while drinking coffee

There are a variety of reasons people choose not to have or use a bank account. According to the FDIC, 5.6 million U.S. households were completely unbanked in 2023.

But the reality is, in today's digital world, relying on cash is becoming an increasingly poor decision. More and more businesses aren’t accepting cash as payment. You lose the ability to grow your money through interest, which is essentially free money. Plus, carrying cash comes with significant risks—if it's lost or stolen, it's gone for good.

The good news is that banking has never been more accessible or beneficial. If you’re looking for a safe place to store, grow, and manage your money, the right financial institution—and accounts—will do just that.

“Banking doesn’t stop you from using cash,” explains Vickie Van Meir, Head of Debit at Mastercard. “It just gives you more opportunity to spend your money and a clearer view of how you’re spending that money.” 

Below, we cover everything you need to know when beginning to explore banking options.

Common Types of Banking Institutions

Traditional Banks

A traditional bank is a for-profit business offering financial services to individuals and businesses. They can range in size from national to regional to community banks.

National Banks

National banks are probably what comes to mind when you think of a bank. These are large, typically well-known institutions with branches across the country. Benefits of a national bank include: 

  • Accessibility: With locations nationwide and, in some cases, internationally, access to a physical branch is usually convenient. This makes it easy to stop by and deposit cash, allowing the bank to quickly digitize it into your account. Plus, widespread ATM access makes it simple to withdraw cash on-the-go.
  • Online banking services: Large banks typically offer advanced banking apps, online tools, and digital features that enhance your experience. These include card controls (allowing you to turn your cards on and off as needed), real-time notifications whenever your card is used, and the ability to easily transfer money between accounts. This makes managing bills and tracking your spending seamless, whether on your phone or laptop.
  • 24/7 customer service: National banks often have larger customer service teams available 24/7, providing multiple ways to contact them—whether by phone, email, or chat. This can be especially helpful if you need quick assistance for any reason.

Regional Banks

The primary difference between national and regional banks is that regional banks are smaller, with branches limited to a specific geographic region. They usually charge lower fees than a national bank (such as monthly maintenance fees, out-of-network ATM fees, or overdraft fees). While they tend to offer slightly more personalized customer experiences, they may not offer 24/7 service, or if they do, it may be automated (like a chatbot).

Community Banks

Community banks typically serve specific communities or towns. They’re known for their personalized service and relationship-driven banking, getting to know their customers and investing in local residents. While they typically have lower fees compared to larger banks, they have fewer branches and ATMs, and sometimes less robust digital banking options. 

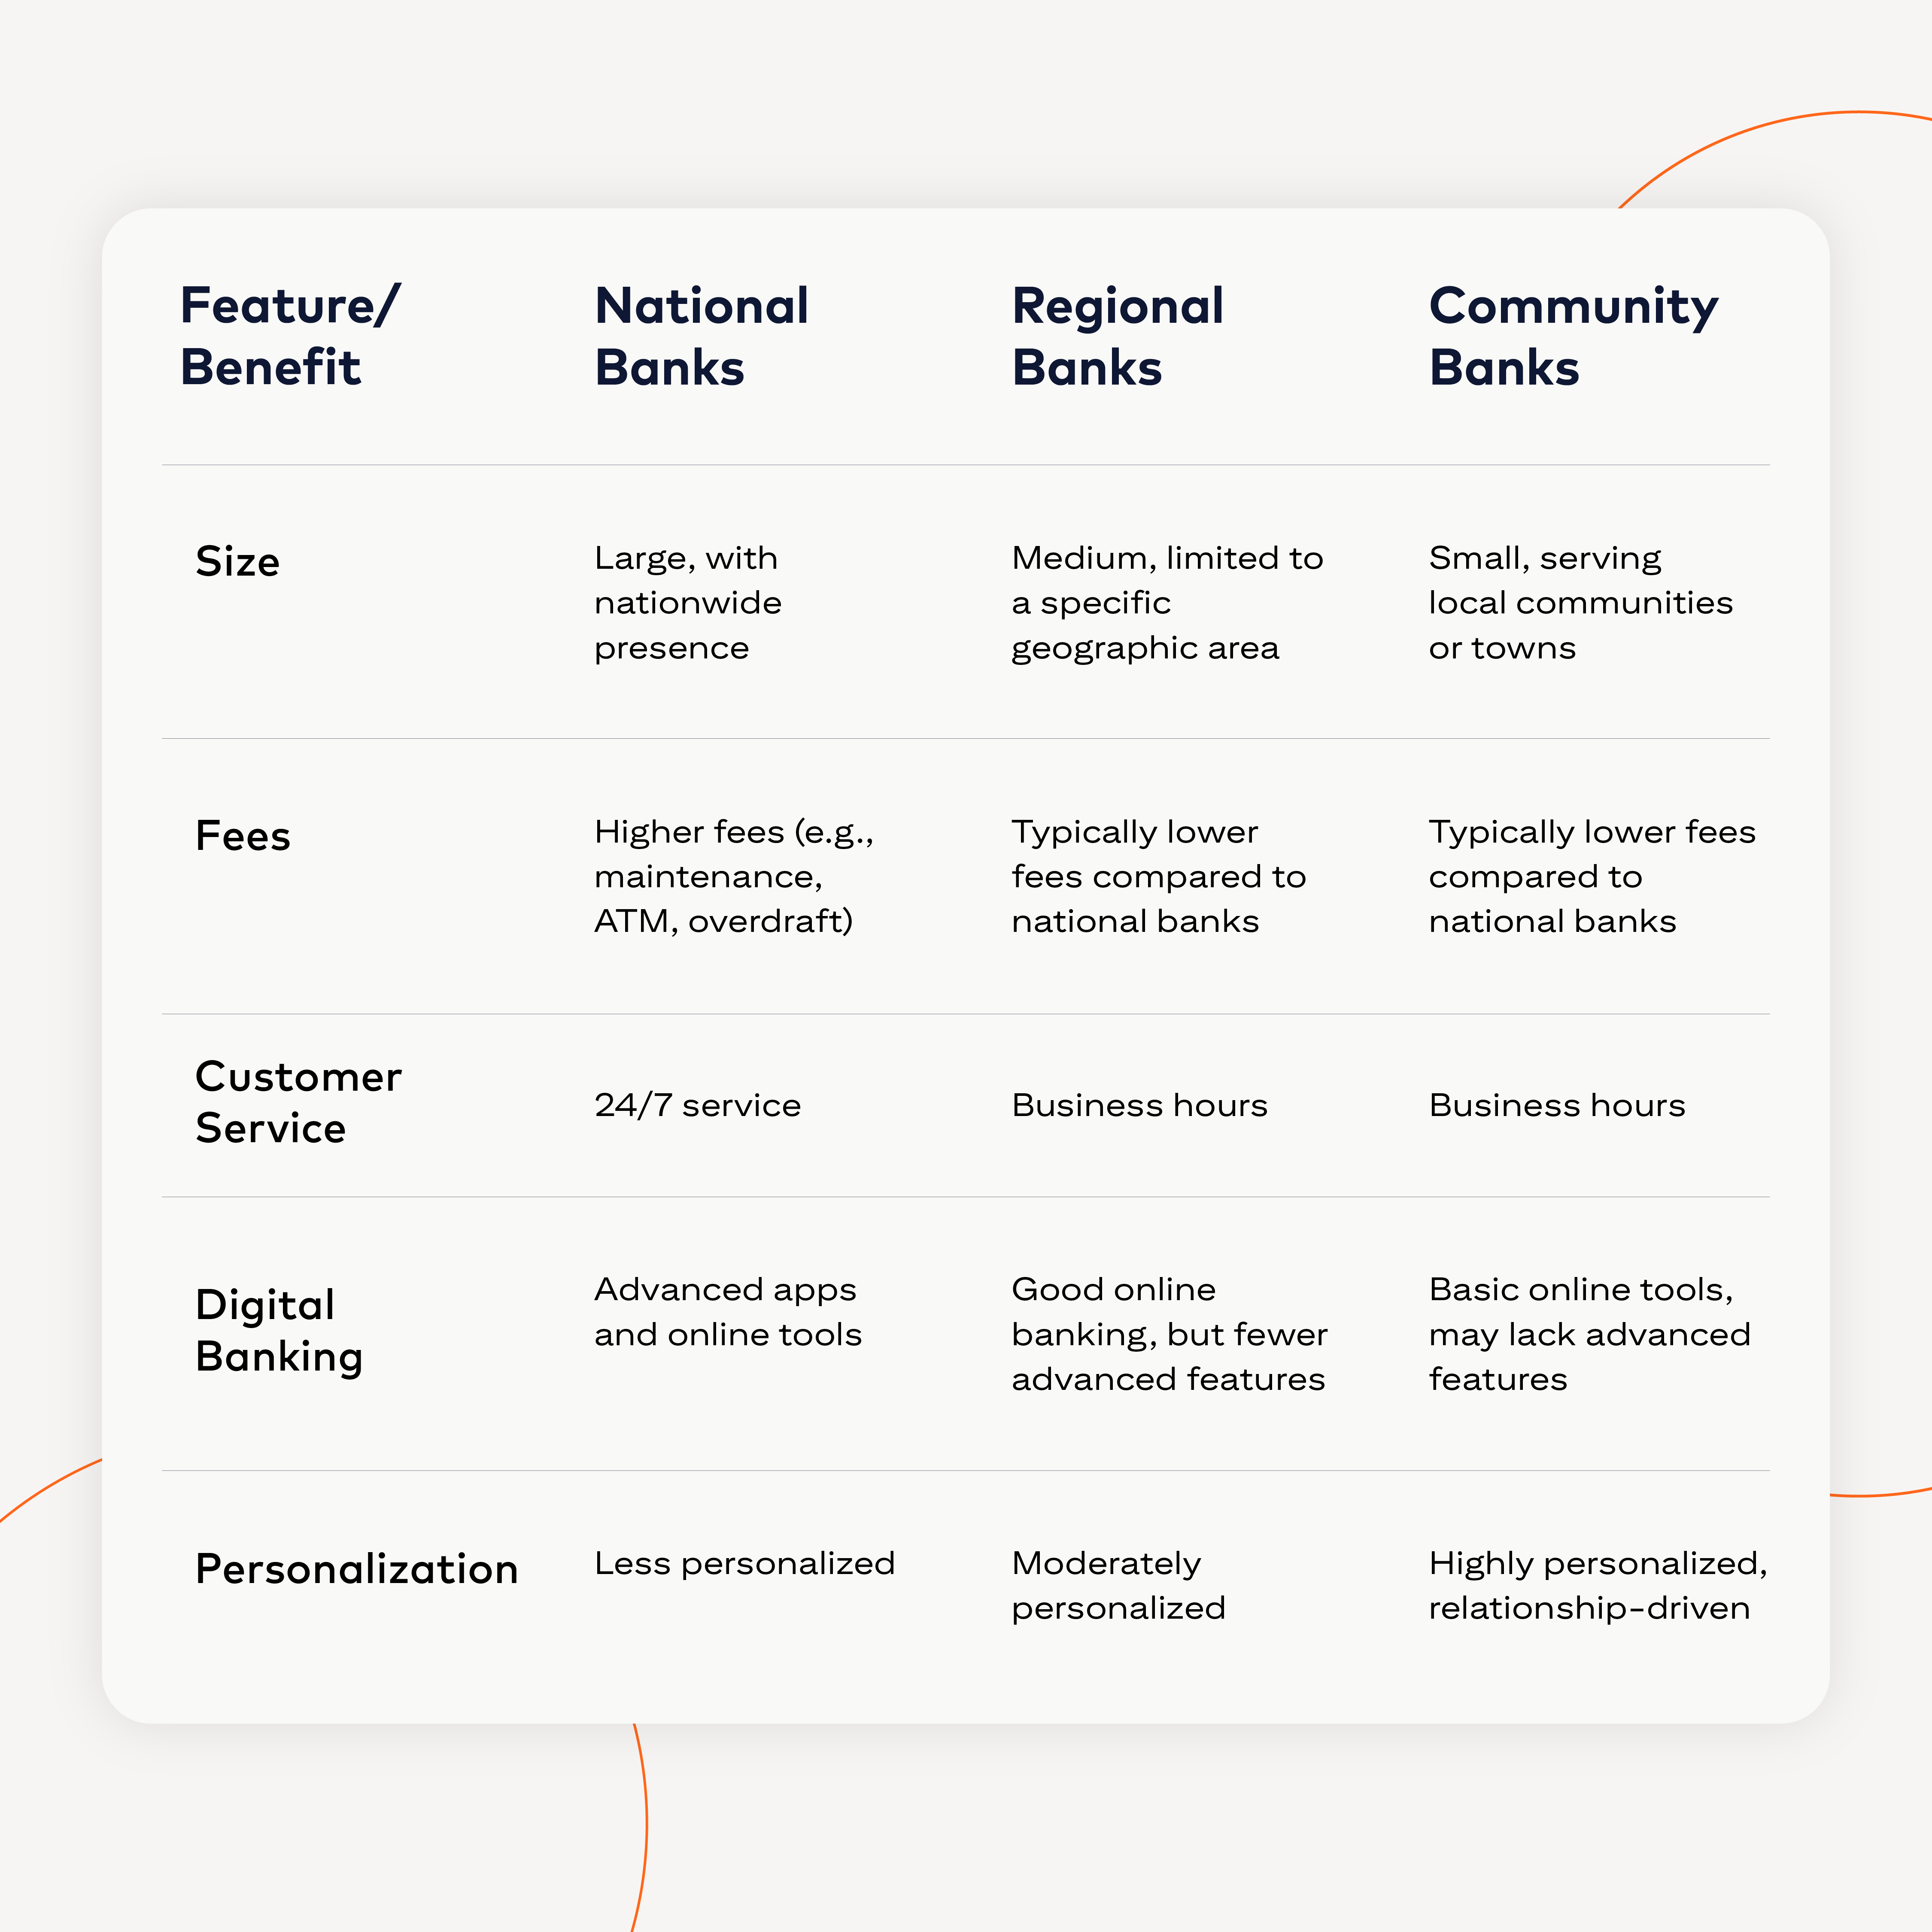
    Comparison Chart between National, Regional, and Community Banks

    Credit Unions

    A credit union is a not-for-profit, members-only financial institution. For example, to join Navy Federal Credit Union, you must be a veteran, retired service member, or active-duty member of the armed forces—or have close ties to someone who is. Other credit unions may have membership requirements based on factors such as your occupation, location, or even religious affiliation.

    Benefits of a credit union include:

    • High interest rates: Credit unions may offer higher interest rates on checking and savings accounts, meaning you can grow your money faster. 
    • Low loan costs: Compared to banks, there are lower expenses or fees associated with taking out a loan.
    • Perks and rewards: Joining a credit union can come with perks including special rates and member-only products.

    Credit unions also pride themselves on creating personalized customer experiences and fostering close relationships with their members. However, they have fewer branches, ATMs and less digital banking options. 

      Online Only Banks

      Online banks refer to banks that are solely digital, meaning they don’t have any physical branches. However, they do typically offer the same products and services as brick-and-mortar banks. With an online bank, you can still take out cash at ATMs using your debit card, but potentially for a small fee. (As a baseline, the average fee for using an out-of-network ATM in 2024 was $4.77).

      Regardless, online banks have some of the highest interest rates and lowest fees on the market. Many also have extra security features, like encryption and multi-factor authentication to protect sensitive information. And of course, online banks are always convenient and accessible, so long as you have a laptop or phone handy.

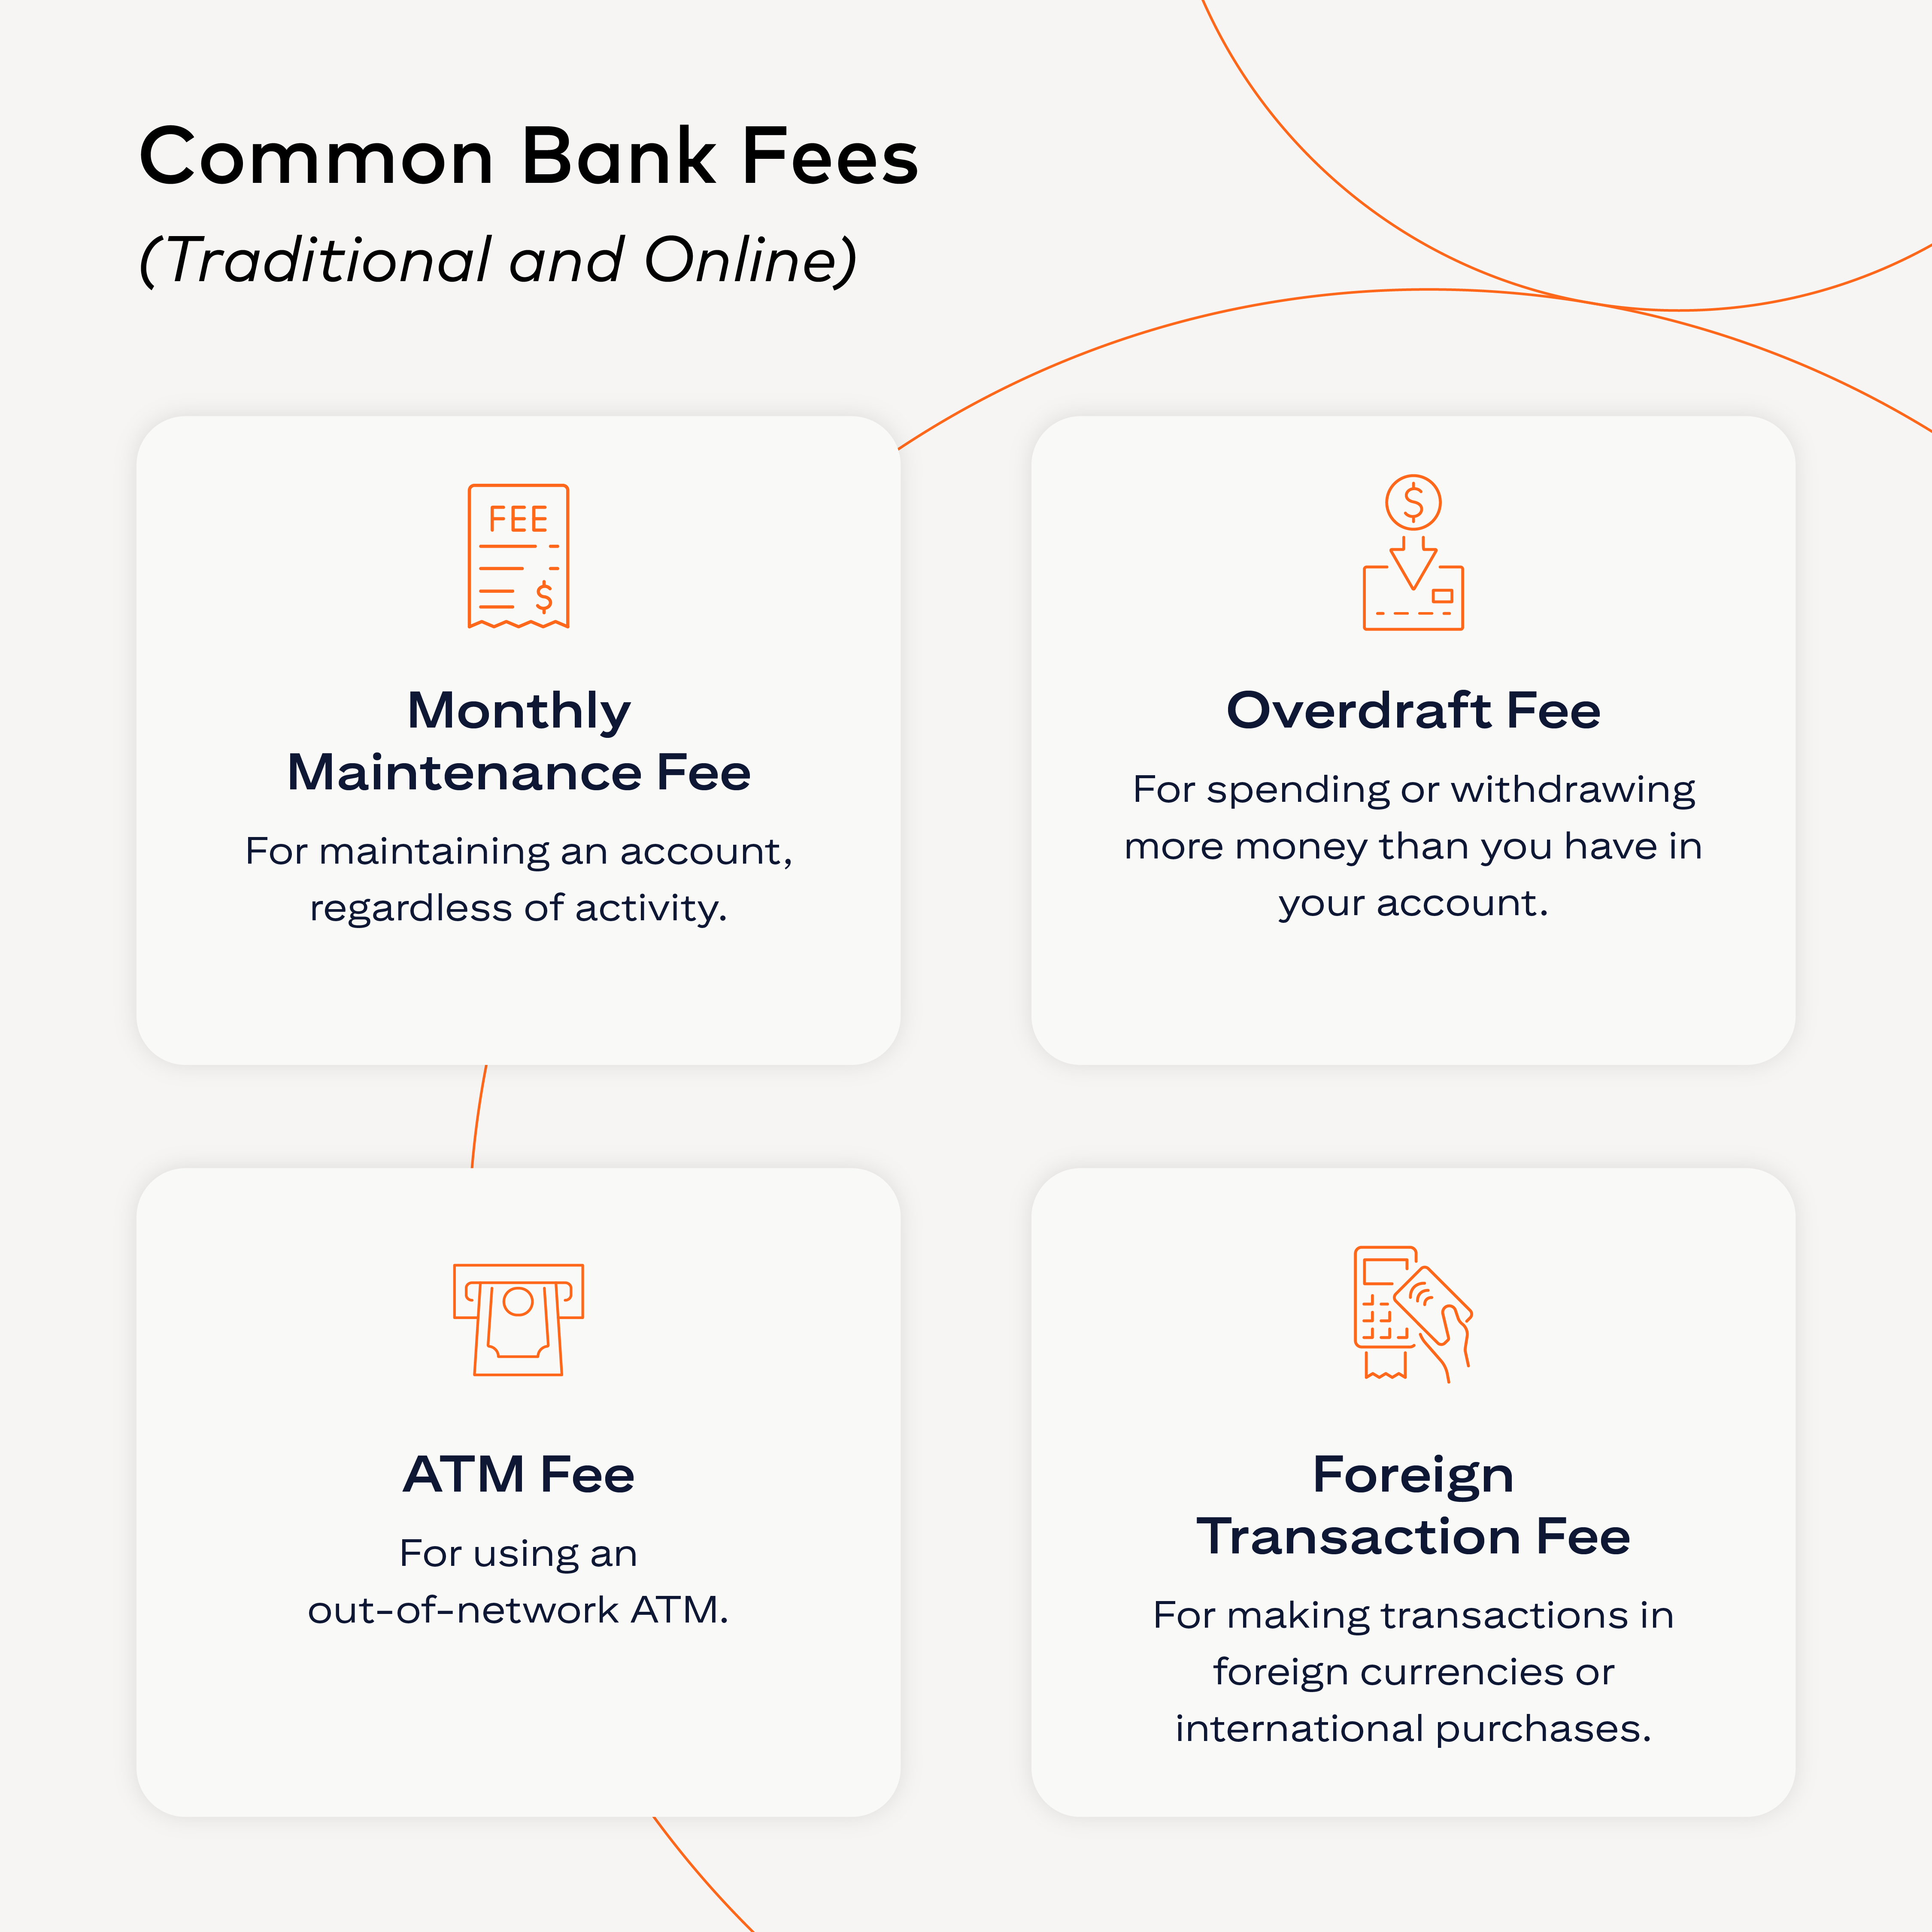
      Common Bank Fees - Monthly, Overdraft, ATM, Foreign Transaction

      Common Types of Bank Accounts

      1. Checking Account

      If you’re new to banking, a checking account is a great place to start. It’s designed for day-to-day transactions including paying bills, making purchases, and withdrawing cash, whether through writing a check, accessing an ATM, or using a debit card. A checking account can also link to payment apps like PayPal, Venmo and Zelle so you can send and receive money digitally.

      Some banks may require you to deposit a minimum amount, like $100 or $250, to open a checking account. If your balance falls below that amount, you could be charged a fee. However, there are also checking accounts available that don’t have a minimum balance or monthly fees.

      If you've had trouble with banking in the past, like overdrawing your account or missing payments, you might qualify for a "second chance" checking account. These accounts are designed to help people rebuild their banking history. If you use the account responsibly over time, you could eventually be eligible for a standard checking account.

      2. Savings Account

      A savings account is a great way to store emergency funds or put away money for future goals. (There are specialty savings accounts, like retirement savings and Health Savings Accounts, for more specific, long-term goals). 

      By keeping this money separate in a dedicated account, it can be less tempting to use for your everyday expenses. Plus, you can earn interest on your money in a savings account.

      There are also high-yield savings accounts, which offer significantly higher interest rates than regular savings accounts. According to U.S. News, the average interest rate on a regular savings account is 0.46%, while interest rates for some high-yield accounts exceed 4.50%.

      Remember: the higher the interest rate on your savings, the more money you’ll make. Many banks and credit unions offer high-yield savings accounts. 

      3. Certificate of Deposit (CD)

      A Certificate of Deposit (CD) is a type of savings account where you agree to leave your money in the bank for a set period of time, like six months or a year. In return, the bank pays you a higher interest rate than regular savings accounts. 

      However, if you take your money out before the agreed time, you’ll pay a penalty, the size of which varies on the bank. However, CDs are low-risk and insured by the government, making them a safe way to grow your savings.

      “CDs are the most restrictive,” says Sebastien Galperti, Vice President of Account Management at Mastercard, “but the upside is significant and there’s even more guarantee than in a regular savings account.”

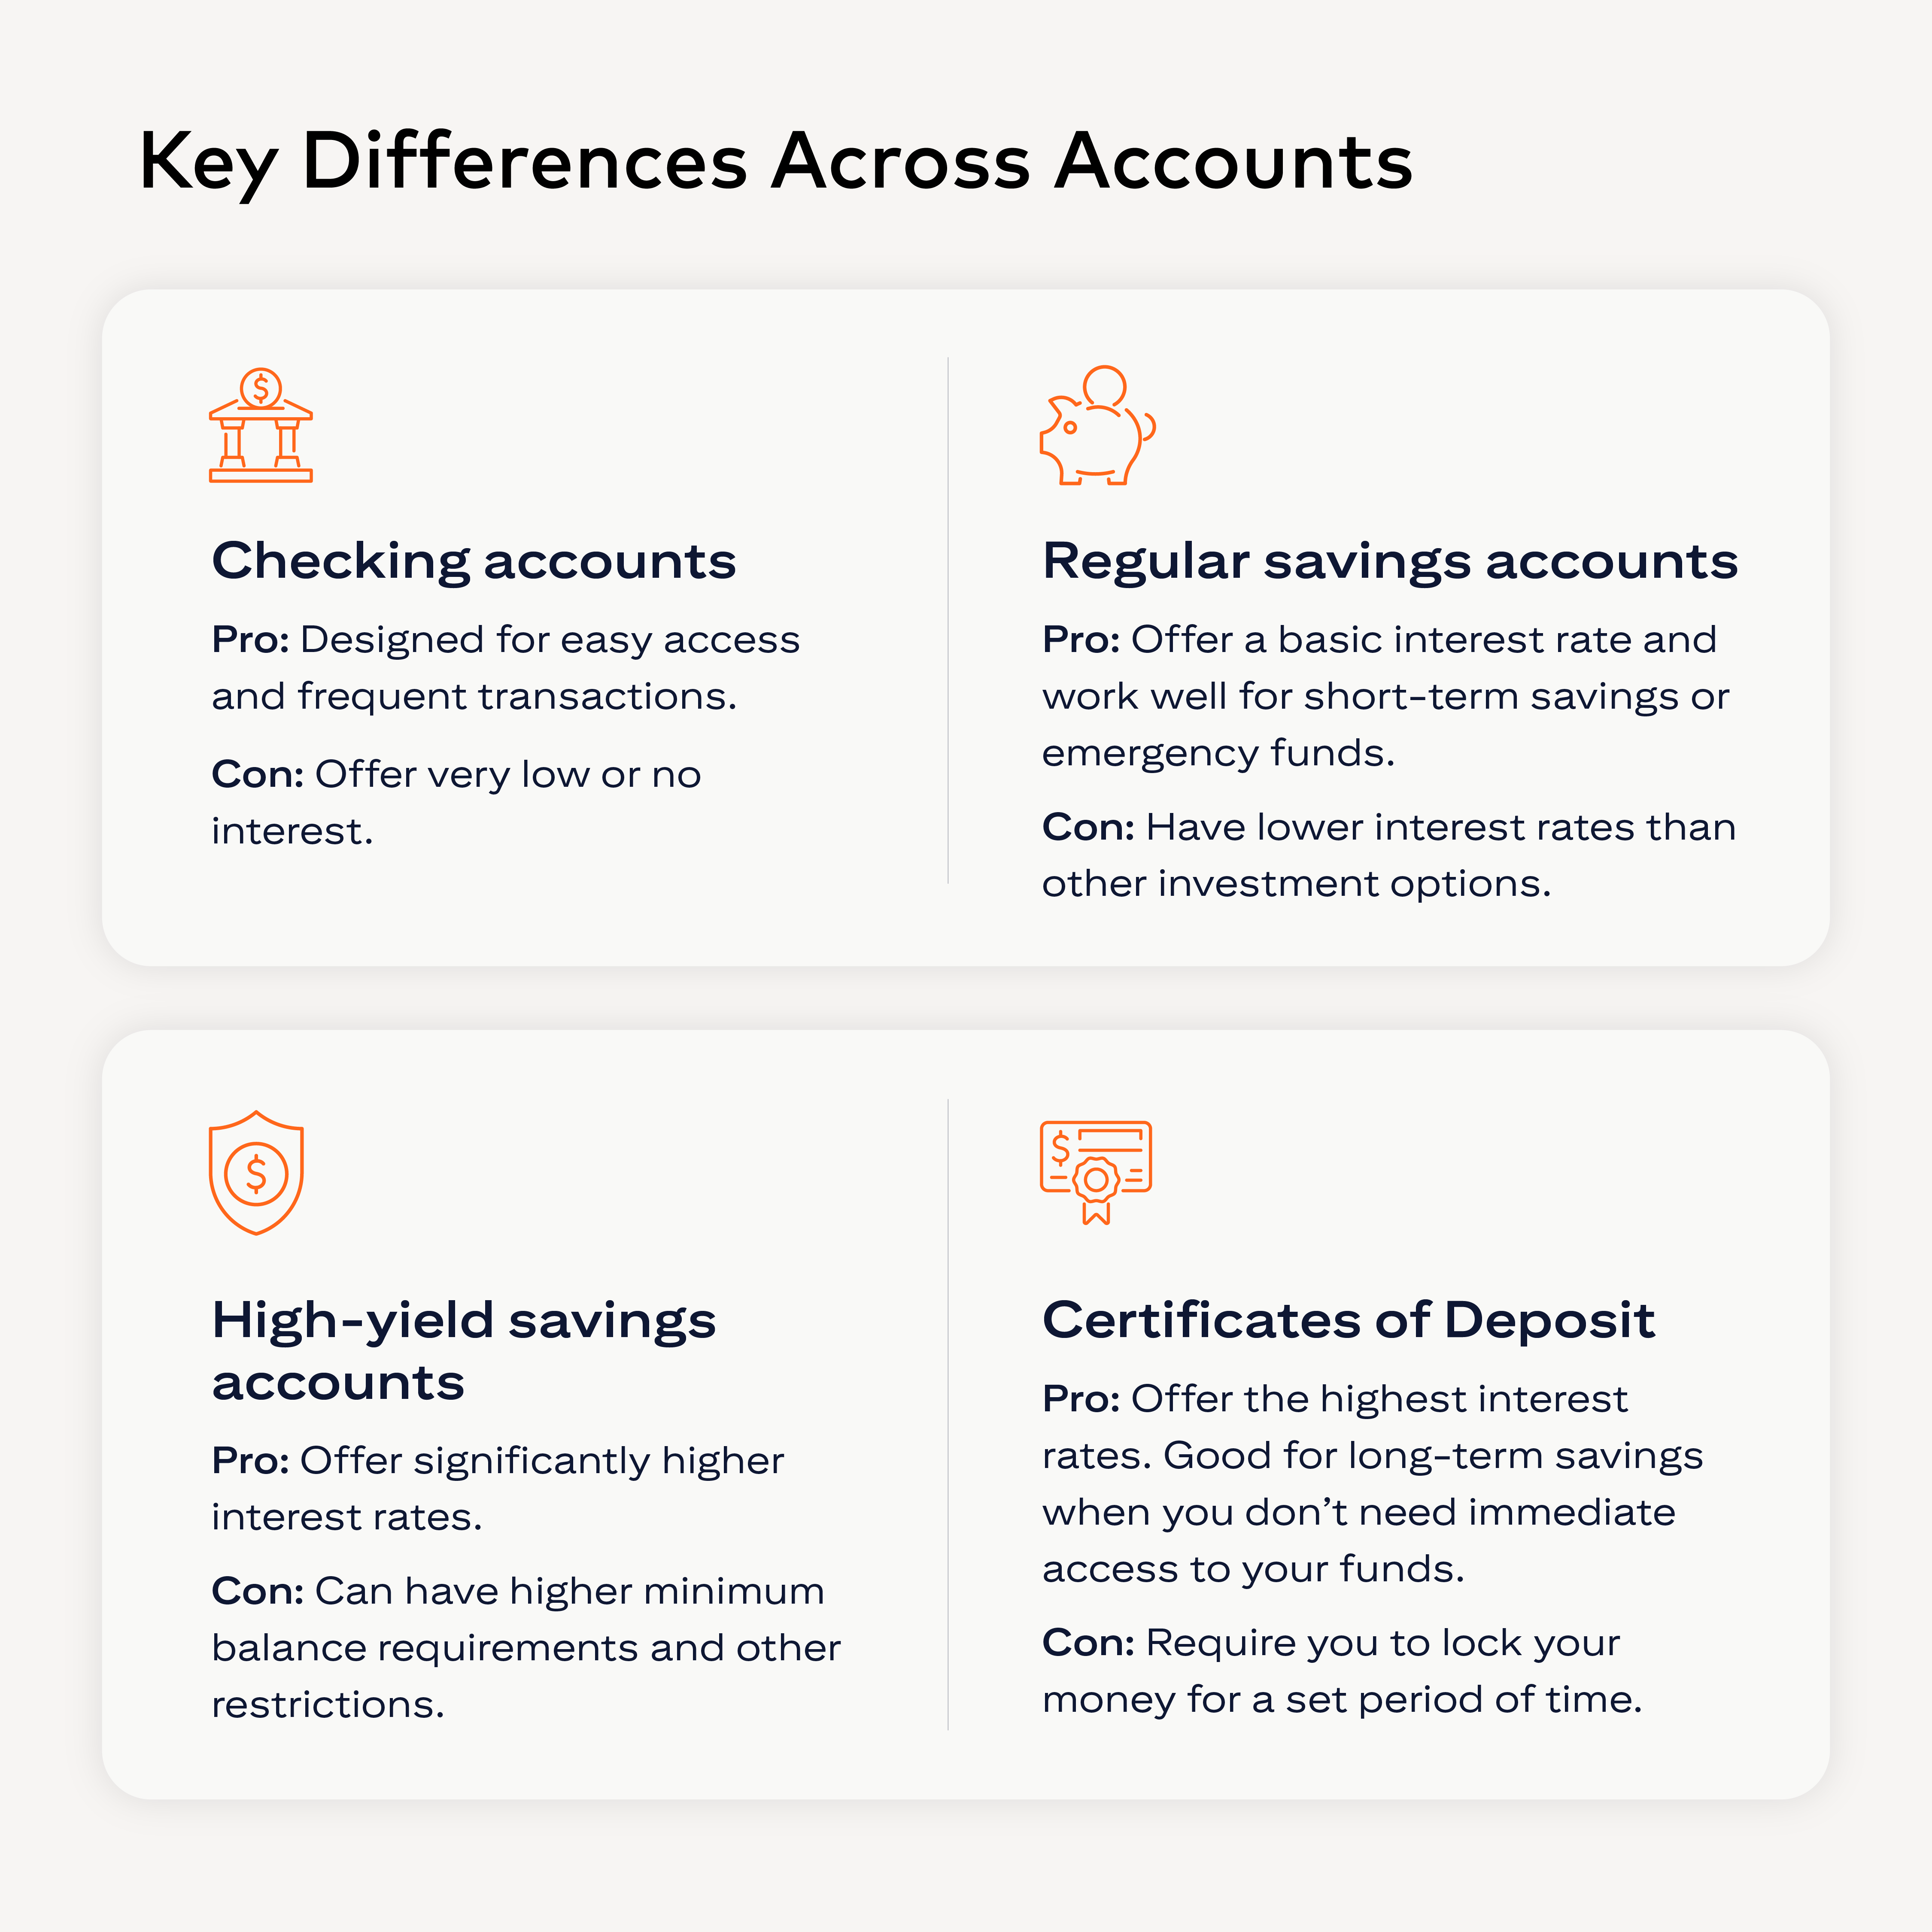
      Key Differences Across Accounts

      Find What Works for You

      Everyone has unique needs, but a reliable bank or credit union is essential if you want to securely store, manage, and grow your money.

      “When considering a financial institution, ask what fees they charge, when those fees are applied, and how you can avoid them, if at all,” Van Meir advises. “Understand what their digital capabilities are and what kind of controls they give you to manage your account in the way that you want to.”

      Remember: Your bank is there to serve you and give you the tools you need to be successful. Don't be afraid to ask questions and take full advantage of all the resources they offer.

      About Master Your Card

      Master Your Card is a community empowerment education program sponsored by Mastercard, that works with committed partners nationwide to bring information about the benefits of electronic payments technology for underserved communities to build brighter financial futures. The program has facilitated presentations and workshops in numerous cities around the country, provided financial education to tens of thousands of students and reached millions through partners’ initiatives and education materials. 

      mastercard logo